
Ally: Bank, Auto & Invest
- Rating
- 4.4
- Downloads
- 1.00M
- Content Rating
- Everyone
Ally: Bank, Auto & Invest - Screenshots
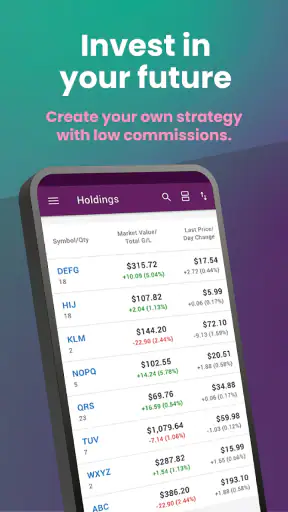
Pros
- Clear overview of checking
- savings
- credit cards
- and investments in one app.
- Spending insights help users track purchases and understand monthly cash flow.
- Mobile check deposit is convenient for handling checks without visiting a branch.
- Custom alerts can help monitor balances
- deposits
- payments
- and unusual activity.
- Ally Invest tools support self-directed trading and portfolio management on mobile.
Cons
- Some advanced investing features may feel limited compared with specialized broker apps.
- Customer support availability and response times may vary by product and issue.
- The app depends heavily on a stable internet connection for account access.
- Users may need separate steps to manage banking and investing account features.
- Investment products involve market risk and may not suit inexperienced investors.
Ally: Bank, Auto & Invest - Description
- App Name
- Ally: Bank, Auto & Invest
- Package Name
- com.ally.MobileBanking
- Developer
- Ally Financial
- Category
- Finance
- Last Updated
- Apr 26, 2012
- Version
- 26.14.0
I approached Ally: Bank, Auto & Invest as a practical finance app rather than something I would open for entertainment. That distinction matters: its value appears when I need to check money, move through a financial task, or keep several parts of my financial life in one place. The app is free, aimed at everyone, and comes from Ally Financial, so its strongest appeal is naturally tied to people who already use Ally or are considering keeping banking, auto financing, and investing connected.
My first impression was that this is an app built around reducing the number of places I need to visit. Instead of treating everyday banking, an auto account, and investments as completely separate experiences, it presents them as parts of one financial relationship. That can make the first week feel especially convenient. The important question, though, is whether that convenience remains useful after the initial setup and curiosity disappear.
What Ally feels like after the first week
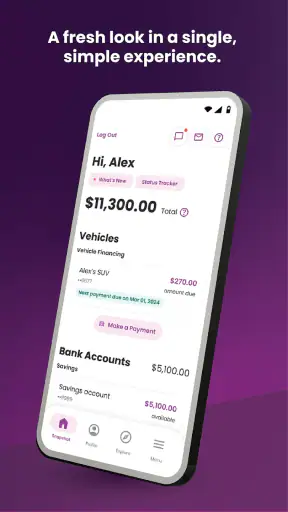
During the first few days, I found the main benefit easy to understand: the app gives me a single mobile starting point for Ally-related financial activity. I do not have to remember which separate service to open when I want to look at a balance or review an account connected to my broader financial picture. For someone who prefers a consolidated view, that is more meaningful than a flashy interface.
The app sits in the finance category, but it is not best understood as a general-purpose budgeting tool for every possible provider. Its usefulness depends heavily on whether Ally is already part of my financial routine. If my checking, savings, auto financing, or investment relationship is elsewhere, the app may still be interesting to explore, but it will not automatically replace the tools I already use.
A realistic first-week scenario would be checking an account before paying a bill, reviewing available money before a larger purchase, and then returning later to confirm that the account activity looks right. I appreciate this kind of repeatable workflow because it does not ask me to learn a complicated system. The app earns attention by being available at the moment a financial decision needs a quick answer.
That simplicity also reveals an important trade-off. A unified financial app can make access feel easier, but it can encourage me to treat a quick balance check as the same thing as actually understanding my spending. I would not rely on the app alone to build a complete household budget unless its tools fit my particular method. For detailed planning, I may still prefer a dedicated budgeting service, a spreadsheet, or the broader financial dashboard I already trust.
The public response gives the app a 4.4 average from around 41 thousand ratings, with more than a million installs. Those figures suggest that it has found a substantial audience, but they do not tell me whether it is the right fit for every banking situation. In my view, the more useful signal is how naturally it fits into a recurring routine: open it, find the relevant account, complete the task, and leave without unnecessary effort.
One subtle strength is the way a combined finance app can support context switching. I might begin by looking at everyday funds and then need to think about an auto payment or an investment position. Having those areas associated with one provider can reduce the mental friction of moving between separate apps. The benefit is greatest for users who genuinely use more than one Ally service, not for someone who only wants a generic spending tracker.
I would also recommend deciding early what I expect the app to do for me. If my goal is simply fast account access, I can judge it by clarity and reliability. If I want long-term financial organization, I need to test whether its account presentation helps me make decisions rather than merely showing information. That distinction prevents the first-week convenience from becoming an exaggerated expectation.
Where the recurring value comes from
After the novelty fades, a finance app has to justify its place through repetition. Ally has a reasonable chance of doing that because financial tasks recur naturally. I may check funds before a transfer, review activity after a purchase, monitor an auto-related obligation, or glance at investments when I am already thinking about my wider finances. These are not one-time features; they are habits that can bring me back.
The app is particularly well suited to people who want a mobile companion for an existing Ally relationship. I do not need a separate reason to open it every day. A few purposeful visits each month may be enough, and that is not a weakness. In finance, an app that helps me complete important tasks quickly can be more valuable than one that tries to keep me engaged constantly.
Its month-to-month value depends on consolidation. If I use only one Ally product, the experience may feel more limited than a broad financial aggregator that pulls information from many institutions. If I use several Ally services, the single-app approach becomes more convincing because I can maintain a clearer connection between short-term cash needs, borrowing responsibilities, and longer-term investing.
This is also where I see a useful trade-off between convenience and independence. Keeping several financial activities with one provider can make the mobile experience smoother, but it may reduce the motivation to compare alternatives. I would still review rates, account terms, investment choices, and borrowing costs separately rather than assuming that a convenient app automatically means every underlying product is best for me.
A practical habit is to give the app a defined job. I might use it for a weekly account review, a monthly check of recurring obligations, and a less frequent look at investments. That routine is more sustainable than opening it repeatedly without a purpose. It also helps me notice whether the app is genuinely improving my decisions or merely satisfying the urge to refresh balances.
For someone managing money with a partner or family, the value may depend on how well the app fits the household’s existing arrangements. A single mobile view can be useful when the relevant accounts are already organized under Ally, but it does not remove the need for shared communication or a separate plan for expenses. I would treat the app as an access and monitoring tool, not as a substitute for agreeing on financial priorities.
How much maintenance it demands
The maintenance burden is relatively easy to underestimate with any finance app. The download is simple because the price is free, but the real upkeep involves keeping login access secure, checking notifications or account activity, and making sure I do not confuse convenience with complete oversight. The app can reduce administrative friction, yet it cannot make financial maintenance disappear.
I would keep my use focused. Rather than browsing every area each time, I would go directly to the task that brought me in, confirm the relevant details, and close the app. This approach reduces fatigue and makes unusual activity easier to notice. It also protects the app from becoming another stream of low-value alerts competing for attention with everything else on my phone.
The current version is 26.14.0 and requires at least operating system 10. That makes compatibility an important practical checkpoint before I depend on it for regular access. Users with older devices should verify that their phone meets the requirement, while people on newer systems should still keep the app and operating system maintained so a financial tool does not become an avoidable weak point in their routine.
I would not describe maintenance as difficult, but it does require discipline. A finance app should be opened with a clear purpose, and I should review activity rather than automatically trusting a familiar screen. If I change phones, adjust security settings, or stop using one of the connected financial services, I should also reconsider whether the app still deserves its prominent place on my home screen.
Another maintenance issue is mental rather than technical: keeping expectations realistic. An app can show balances and account information, but I remain responsible for understanding what those numbers mean. A rising investment value is not the same as guaranteed progress, and a comfortable current balance does not necessarily account for upcoming obligations. Ally can support the review; it cannot perform the judgment for me.
What may cause fatigue over time
The biggest source of fatigue is likely to be relevance. If I rarely use Ally’s broader financial services, I may find myself opening the app for one narrow purpose and ignoring much of what surrounds it. In that situation, a specialized banking app or a neutral money-management tool could feel more efficient because it would be centered on the exact task I perform most often.
Another possible frustration is the tension between a unified experience and the different ways people think about money. Banking, auto financing, and investing are related, but they do not require the same kind of attention. Everyday spending calls for quick clarity, an auto obligation calls for payment awareness, and investing calls for patience. When these areas share one app, I still need to mentally separate them.
I also would not choose this as my only financial planning system if I need deep analysis across many institutions. A general aggregator may be better for someone whose accounts are spread across several banks, brokerages, and lenders. A dedicated investment platform may be preferable for a user who mainly researches securities and portfolio details. Ally’s advantage is connection within its own ecosystem, not universal coverage.
There is a quieter kind of fatigue that comes from checking too often. Finance apps make it easy to turn normal market movement or ordinary account changes into a source of unnecessary worry. I prefer using the app to support scheduled reviews and concrete decisions. For investments especially, frequent glances can encourage emotional reactions that have little to do with a sound long-term plan.
Users who want a completely provider-neutral experience should think carefully before making this their central money app. Its identity is closely tied to Ally Financial, which is helpful when my accounts are there and less compelling when they are not. I would skip it as a primary tool if my main requirement is a single dashboard spanning unrelated institutions or a highly specialized budgeting workflow.
That said, fatigue is not inevitable. The app becomes easier to live with when I limit it to the areas that matter, silence distractions that do not help me, and establish a predictable review rhythm. The recurring value comes from reducing friction around genuine financial tasks, not from maximizing screen time.
Who should keep it installed
I think Ally is a strong candidate for people who already use Ally for more than one financial need and want a mobile hub instead of several disconnected routines. It is also a sensible choice for someone who values straightforward access and prefers a finance app that supports regular check-ins without demanding elaborate setup.
It may be less suitable for a user who wants a full budgeting coach, extensive cross-bank analysis, or an investment-first research environment. Those needs point toward more specialized alternatives. Choosing a different app would not mean Ally is poor; it would mean the user is prioritizing breadth, analysis, or portfolio tools over provider-centered convenience.
The age rating is Everyone, which matches the app’s practical subject matter, though responsible use still matters because financial decisions affect real commitments. I would encourage a new user to begin with observation: confirm that the accounts appear as expected, learn where the important information lives, and only then build the app into recurring money routines.
For me, the strongest long-term test is simple: does opening the app help me complete a financial check with less uncertainty and less wasted time? If yes, it earns its place. If I open it and still need several other tools to understand my situation, its role should remain narrow rather than becoming the center of my financial life.
My long-term verdict
Ally succeeds less through novelty than through the possibility of a dependable habit. Its free access, broad financial focus, and connection to Ally Financial make it useful for the right customer, especially one who wants banking, auto, and investing relationships within one mobile experience. The app’s lasting value comes from repeated practical use, not from features I would explore once and forget.
My recommendation is therefore conditional but positive. If Ally is already part of my financial world, I would keep the app installed and give it a defined role in my monthly routine. I would use it to monitor accounts, handle timely checks, and maintain awareness, while relying on separate tools or personal planning methods when I need deeper budgeting or cross-provider analysis.
The app earns lasting space when it reduces everyday financial friction without pretending to replace financial judgment. That is a modest promise, but a useful one. Users who fit its ecosystem can reasonably expect recurring convenience. Users who need a neutral, highly analytical, or investment-specialist platform should look elsewhere. After the first-week appeal fades, that honest division is what makes the app worth considering.
FAQ
What is Ally: Bank, Auto & Invest used for?
Ally: Bank, Auto & Invest brings several financial services into one mobile app. After signing in, users can manage eligible Ally Bank accounts, review balances and transactions, move money, deposit checks, and access selected Ally Invest or Ally Auto features. The exact tools available depend on the products you have, your account status, and your location, so it is worth checking eligibility before downloading.
Is the Ally app safe for banking and investing?
The app includes standard security features designed to protect financial information, such as secure sign-in, account monitoring, alerts, and additional verification options when required. However, no banking application is completely risk-free. Download it only from the official Google Play Store or Apple App Store, keep your phone and operating system updated, avoid public Wi-Fi for sensitive actions, and never share passwords or verification codes.
Can I open an Ally account directly from the app?
In many cases, the app can guide new customers through applications for eligible Ally products, including certain bank, investing, or auto-related services. Approval is not automatic, and requirements may include identity verification, personal information, credit checks, funding details, or other documentation. Product availability and application options can change, so confirm the current terms and eligibility during the sign-up process.
What banking features are available in Ally: Bank, Auto & Invest?
Depending on the Ally products connected to your profile, you may be able to view account balances, transfer money, pay bills, deposit checks with your phone camera, manage debit-card settings, receive notifications, and review statements. Customers with eligible investment accounts may also see portfolio information and place supported trades. Some features, limits, processing times, and fees vary by account type.
Does Ally: Bank, Auto & Invest charge fees for using the app?
Downloading the application is generally separate from the fees or terms associated with Ally’s financial products. The app itself may not require a subscription, but actions such as investing, transfers, expedited services, or specific account activities can be subject to product rules, market costs, or third-party charges. Review the fee schedule and account agreement carefully, because rates and conditions may change.


